On this page
- 01Key takeaways
- 02What should an insurance broker's website include?
- 03How should FCA status be shown?
- 04What complaints information is needed?
- 05What do customers want to know?
- 06Which rules apply to website content?
- 07When is more detail unnecessary?
- 08What does this look like in practice?
- 09Insurance broker website checklist
- 10Next step
- 11Sources and further reading
- 12Frequently asked questions
Key takeaways
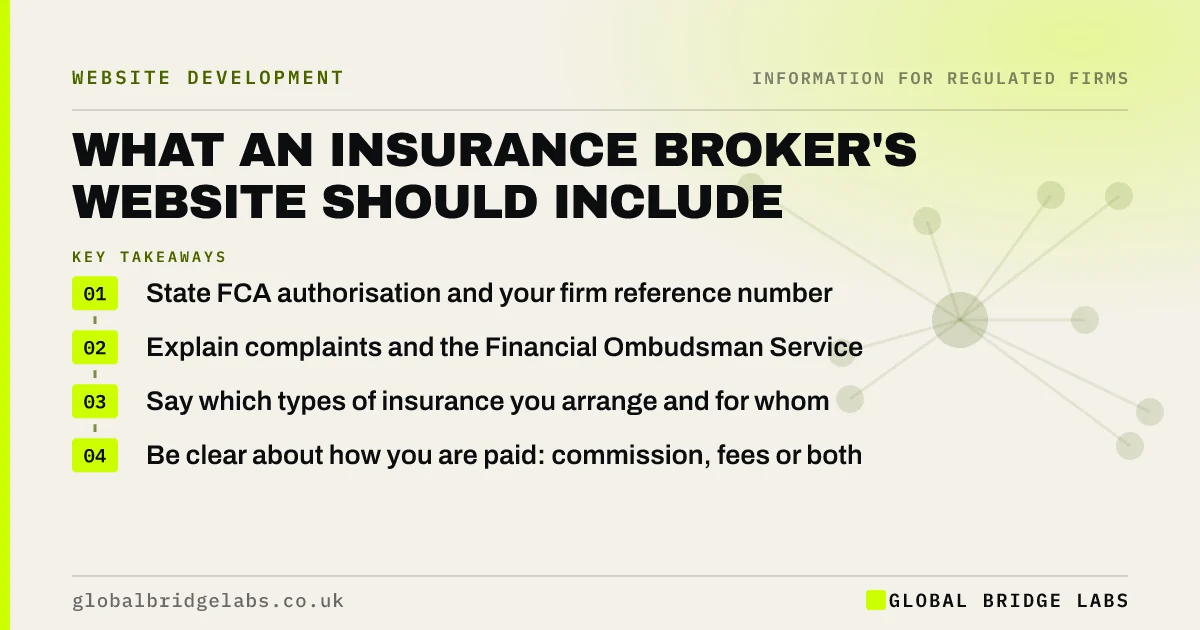
An insurance broker's website should show its FCA authorisation status and firm reference number, complaints handling and Financial Ombudsman Service details, the types of insurance you arrange, who you serve, and how you are paid. Promotions must be fair, clear and not misleading, and the Consumer Duty expects communications customers can understand.
- State FCA authorisation and your firm reference number.
- Explain complaints and the Financial Ombudsman Service.
- Say which types of insurance you arrange and for whom.
- Be clear about how you are paid: commission, fees or both.
Running a broker website? Message us on WhatsApp.
Chat on WhatsApp →What should an insurance broker's website include?
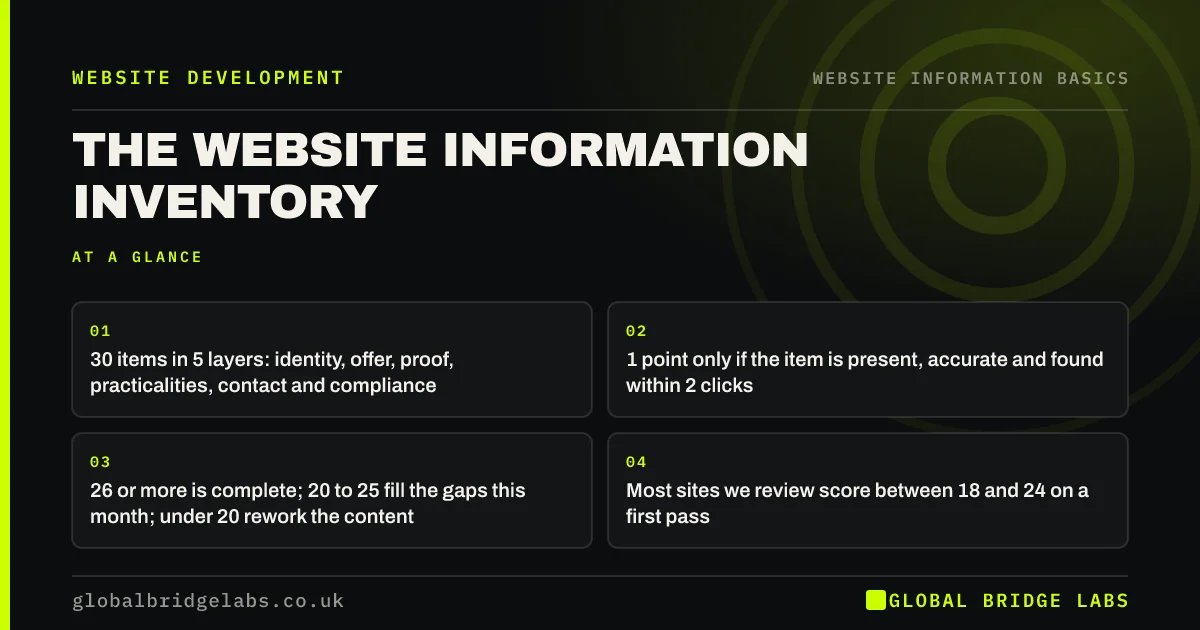
An insurance broker's website should include FCA status and firm reference number, complaints and ombudsman information, the types of cover you arrange, the customers you serve, how you are paid and how to get a quote. Global Bridge Labs (GBL) treats the status statement as the regulated item on top of the 30-item inventory.
How should FCA status be shown?
Use your regulatory status statement as the FCA expects, with your firm reference number, in the footer of every page. Appointed representatives should name their principal. Link to your FCA Register entry so customers can check it in one click.
What complaints information is needed?
FCA-regulated firms must handle complaints under the FCA's rules and tell eligible customers about the Financial Ombudsman Service. Publish how to complain, your timescales and the ombudsman route on a complaints page linked from the footer.
What do customers want to know?
Customers want to know whether you cover their type of risk, whether you search the market or use a panel, how renewals and claims support work, and how you are paid. Commercial clients also want to see sector expertise. Answer these plainly on service pages.
Which rules apply to website content?
Financial promotions must be fair, clear and not misleading, and the Consumer Duty expects firms to support customer understanding. Avoid absolute claims such as 'cheapest quotes guaranteed' unless you can prove them. Check promotional content against FCA guidance before publishing.
When is more detail unnecessary?
Detailed policy wordings and insurer terms are not needed on the website for most brokers; they belong in quote documents. Overloading pages with regulatory text can bury the information customers need. Keep required disclosures clear and concise.
What does this look like in practice?
A pattern we see in broker websites: the FCA status line exists but the complaints route and ombudsman details sit only in terms of business PDFs. A short complaints page linked from every footer fixes a common gap in minutes.
Insurance broker website checklist
- Show FCA status and firm reference number.
- Link to your FCA Register entry.
- Publish complaints and ombudsman details.
- List types of cover and customers served.
- Explain how you are paid.
- Check promotions are fair, clear and not misleading.
Next step
Check your footer status statement against the FCA's current wording and your Register entry, then confirm the complaints route is one click away.
Message us on WhatsApp for a broker website review, with no pitch.
Chat on WhatsApp →Sources and further reading
- Financial Services Register · Financial Conduct Authority
- Financial promotions and adverts · Financial Conduct Authority
- Our approach to resolving complaints · Financial Ombudsman Service
- Consumer Duty · Financial Conduct Authority
Frequently asked questions
What must an FCA-regulated firm show on its website?
It should show its regulatory status and firm reference number, complaints handling information and Financial Ombudsman Service details where relevant. Promotions must be fair, clear and not misleading. Check the FCA's current requirements for your permissions.
Should an insurance broker show which insurers it uses?
Saying whether you search the whole market or use a panel helps customers understand your service and is part of being clear about the nature of what you offer. Many brokers name key insurer partners.
Do brokers need to explain commission on their website?
Being open about how you are paid, whether commission, fees or both, supports the FCA's expectations on transparency and customer understanding. Your terms of business should give the detail, and the website should summarise it in plain words.
Written by
Global Bridge Labs (GBL) is a UK–Sri Lanka partner for social media, websites and BPO. Everything here comes from client delivery, not theory.