On this page
Key takeaways
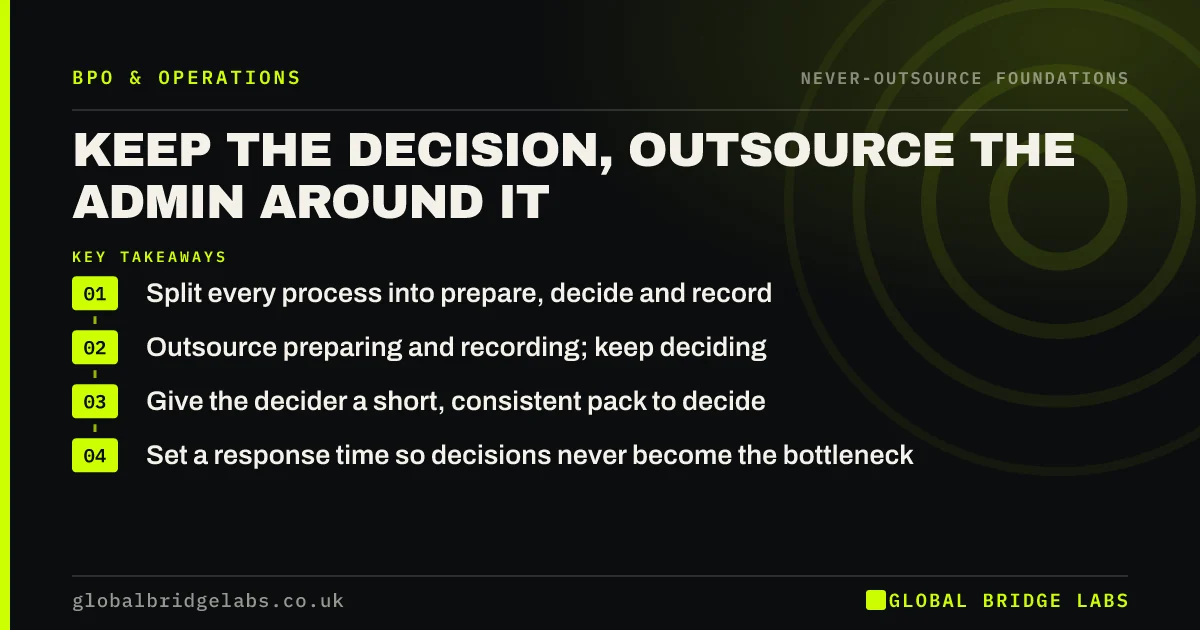
In a business insurance review, a broker can compare policies and advise, and an outsourced team can collect the information insurers ask for. But the decisions on what to cover, how much and what to tell the insurer stay with you. Businesses must make a fair presentation of the risk, and most employers must hold employers' liability cover of at least £5 million.
- Owners decide cover levels and which risks to accept.
- Employers' liability insurance of at least £5 million is usually compulsory.
- You must disclose material facts to the insurer.
- Outsource renewal admin: data, reminders and document filing.
Want your insurance renewal information gathered for you? Message us on WhatsApp.
Chat on WhatsApp →Why are cover decisions yours?
Because insurance decides which risks the business carries itself. Choosing an excess, a sum insured or whether to buy cyber cover is a risk appetite decision. A broker earns commission or fees and can advise well, but only the owners know what loss the business could survive.
What must you tell the insurer?
Under the Insurance Act 2015, business customers have a duty of fair presentation: to disclose every material circumstance the business knows or ought to know, after a reasonable search. A broker helps, but the business supplies the facts. Getting this wrong can reduce or void a claim.
Which renewal admin can be outsourced?
Most of it. An outsourced team can track renewal dates, gather turnover, payroll, vehicle and claims data, chase internal owners for updates, compare quotes against last year and file certificates. This makes renewals calmer and more accurate.
- Renewal reminders at 90, 60 and 30 days.
- Collecting turnover, payroll and asset data.
- Claims history and incident logs.
- Filing policies and certificates.
When should you review cover in the year?
When anything material changes: new premises, a new service line, a big contract with insurance requirements, more staff, overseas work or a new outsourcing arrangement. Contracts with clients often specify minimum cover, so check before you sign.
What does this look like in practice?
A pattern we see: policies roll over for years without review, and cover no longer matches what the business does. A yearly review with data gathered in advance lets owners make deliberate choices.
Insurance review checklist
- List every policy, renewal date and limit.
- Check employers' liability is in place.
- Update the facts insurers rely on.
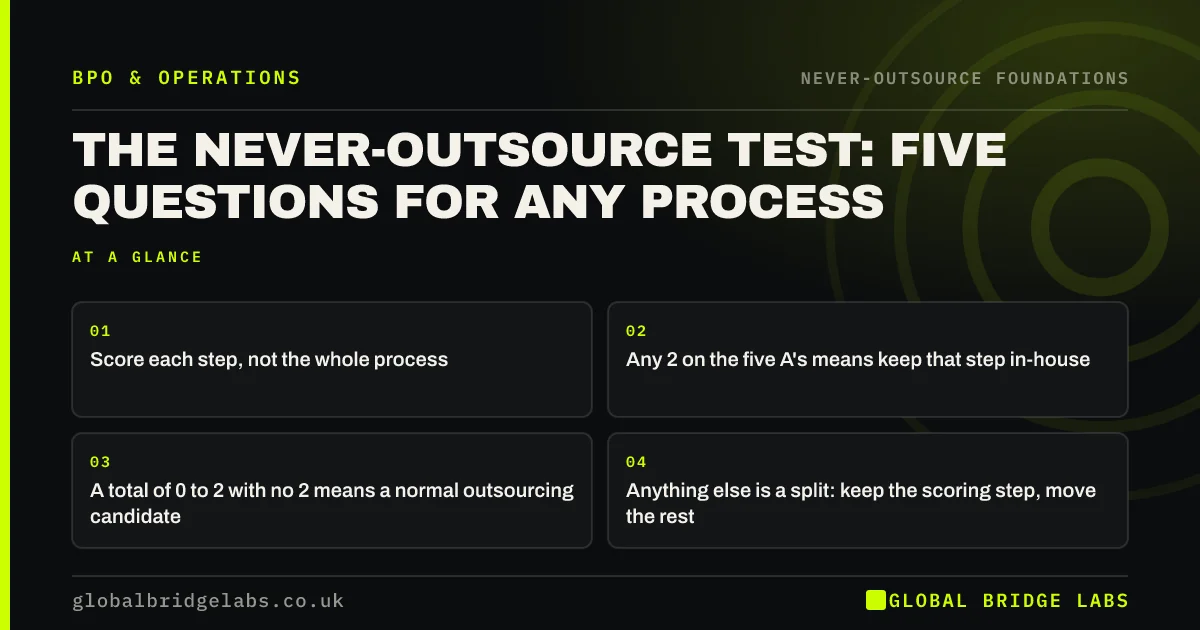
- Decide cover levels and excesses yourself.
- Review after any material change.
Next step
List your policies and renewal dates on one page. Mark any where the business has changed since the last renewal.
Message us on WhatsApp, or book a 30-minute consultation.
Chat on WhatsApp →Sources and further reading
- Employers' liability insurance · GOV.UK
- Health and safety basics for your business · Health and Safety Executive
Frequently asked questions
Is employers' liability insurance compulsory in the UK?
For most employers, yes. If you employ staff, you usually need employers' liability insurance with cover of at least £5 million from an authorised insurer, and you can be fined for not having it. Some family businesses and other exceptions apply; check GOV.UK guidance.
What is the duty of fair presentation?
Under the Insurance Act 2015, a business buying insurance must disclose every material circumstance it knows or ought to know after a reasonable search, in a clear and accessible way. Failing to do so can lead an insurer to reduce or refuse a claim.
Can insurance admin be outsourced?
Yes. Tracking renewal dates, gathering information for insurers, comparing quotes, logging claims and filing documents are routine tasks. Decisions on cover levels, excesses and what risks to insure stay with the owners, who may take a broker's advice.
Written by
Global Bridge Labs (GBL) is a UK–Sri Lanka partner for social media, websites and BPO. Everything here comes from client delivery, not theory.