On this page
- 01Key takeaways
- 02What does auto-enrolment admin involve?
- 03What are the key auto-enrolment rules?
- 04Which parts can be outsourced?
- 05What happens if auto-enrolment admin goes wrong?
- 06What does this look like in practice?
- 07Auto-enrolment checklist
- 08Next step
- 09Sources and further reading
- 10Frequently asked questions
Key takeaways
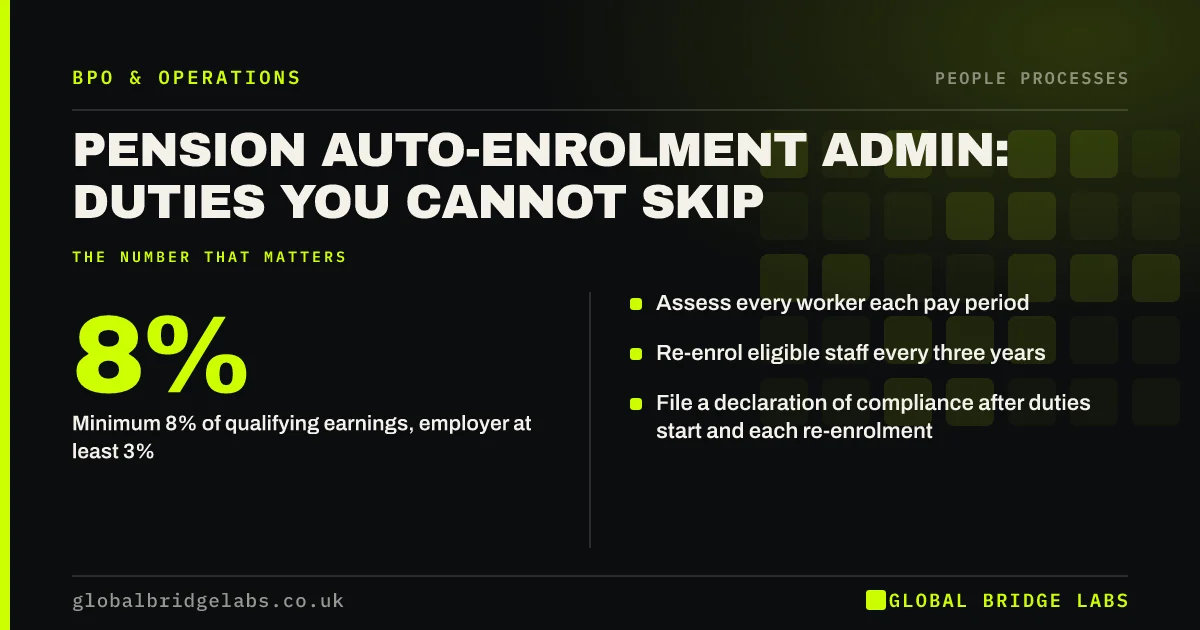
Auto-enrolment admin is a legal duty for every UK employer, and The Pensions Regulator enforces it. Eligible jobholders, aged 22 to State Pension age and earning over £10,000 a year, must be enrolled, with a minimum total contribution of 8% of qualifying earnings, of which the employer pays at least 3%. The admin outsources well; the employer stays responsible.
- Assess every worker each pay period.
- Minimum 8% of qualifying earnings, employer at least 3%.
- Re-enrol eligible staff every three years.
- File a declaration of compliance after duties start and each re-enrolment.
Want your auto-enrolment routine checked? Message us on WhatsApp.
Chat on WhatsApp →What does auto-enrolment admin involve?
Assessing workers' age and earnings each pay period, enrolling eligible jobholders, writing to staff about their rights, processing opt-outs and refunds, deducting and paying contributions on time, handling requests to join, re-enrolling every three years and filing declarations of compliance. Most of it runs through payroll each month.
What are the key auto-enrolment rules?
Workers aged 22 to State Pension age earning over £10,000 a year must be enrolled. Minimum contributions total 8% of qualifying earnings, with the employer paying at least 3%. Staff can opt out, usually within a month of enrolment, and get a refund. Every three years you must re-enrol eligible staff who left the scheme and file a re-declaration of compliance with The Pensions Regulator.
- Eligible: aged 22 to State Pension age, earning over £10,000.
- Contributions: 8% total, employer at least 3%.
- Opt-outs: refund if within the opt-out period.
- Re-enrolment and re-declaration every three years.
Which parts can be outsourced?
Almost all of the processing: assessment, enrolment letters, opt-out handling, contribution uploads to the pension provider, the re-enrolment exercise and preparing the declaration. The employer must approve the declaration, choose the scheme and stay responsible for compliance, because duties cannot be transferred to a provider.
- Employee benefits admin: enrolments, changes and P11Ds
- Regulated processes: outsource the work, keep the duty
Want a calendar of your auto-enrolment dates? Message us on WhatsApp.
Chat on WhatsApp →What happens if auto-enrolment admin goes wrong?
The Pensions Regulator can issue compliance notices, fixed penalties and escalating daily penalties for continued failure, and can require you to pay missed contributions. Most problems in small firms come from late contribution payments, missed re-enrolment dates or new starters not assessed.
What does this look like in practice?
A pattern we see: auto-enrolment runs fine for years, then the three-year re-enrolment date arrives and nobody remembers what to do. A dated compliance calendar with re-enrolment on it prevents the scramble.
Auto-enrolment checklist
Run these every pay period and every three years.
- Assess all workers each pay period.
- Send required letters on time.
- Process opt-outs and refunds promptly.
- Pay contributions by the deadline.
- Diary the re-enrolment date.
- File the re-declaration of compliance.
Next step
Tell us when your duties started and how payroll handles pensions today. We will tell you what an auto-enrolment routine should include and what we could run.
Message us on WhatsApp, or book a 30-minute consultation.
Chat on WhatsApp →Sources and further reading
- Automatic enrolment and pension duties for employers · The Pensions Regulator
- Set up and manage a workplace pension scheme · GOV.UK
- Workplace pensions: what you, your employer and the government pay · GOV.UK
Frequently asked questions
Who must be auto-enrolled into a workplace pension?
Workers aged between 22 and State Pension age who earn more than £10,000 a year and work in the UK must be automatically enrolled. Other workers may have the right to opt in or join. Employers must assess workers every pay period, as ages and earnings change.
How often must employers re-enrol staff?
Every three years. Employers must re-enrol eligible staff who have left the scheme or reduced contributions below the minimum, then complete a re-declaration of compliance with The Pensions Regulator, usually within five months of the re-enrolment date.
Can auto-enrolment admin be outsourced?
The admin can, often through a payroll provider: assessment, letters, opt-outs, contribution uploads and re-enrolment. The employer remains legally responsible for compliance, chooses the scheme and must approve the declaration of compliance.
Written by
Global Bridge Labs (GBL) is a UK–Sri Lanka partner for social media, websites and BPO. Everything here comes from client delivery, not theory.