On this page
- 01Key takeaways
- 02What breaks in finance as a business grows?
- 03Which finance work scales with volume?
- 04What must stay under your control?
- 05How does chasing payments affect growth?
- 06What does scaling finance this way cost?
- 07When should you build finance in-house?
- 08What does this look like in practice?
- 09Scaling finance checklist
- 10Next step
- 11Sources and further reading
- 12Frequently asked questions
Key takeaways
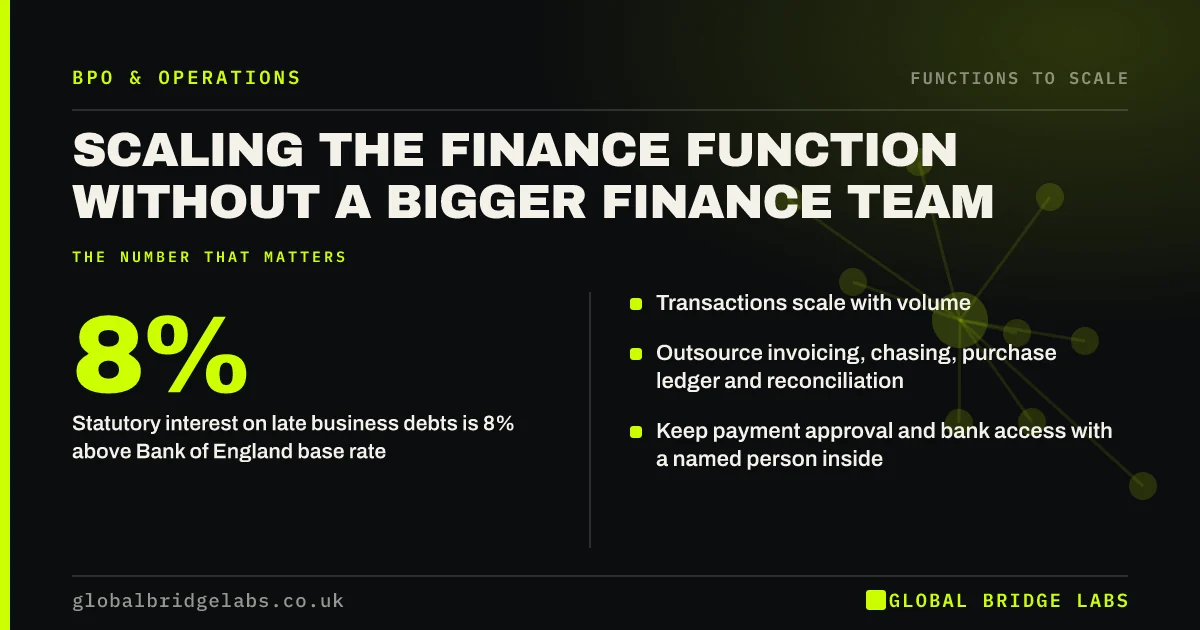
To scale the finance function in a small business, separate transaction processing from financial control. Invoicing, payment chasing, purchase ledger and reconciliations grow with volume and can run through a managed team. Approval, cash decisions and reporting to the owner stay inside, often with a part-time finance lead.
- Transactions scale with volume. Control does not.
- Outsource invoicing, chasing, purchase ledger and reconciliation.
- Keep payment approval and bank access with a named person inside.
- Statutory interest on late business debts is 8% above Bank of England base rate.
Month end taking longer every month? Message us on WhatsApp with your invoice volumes.
Chat on WhatsApp →What breaks in finance as a business grows?
As a business grows, the number of invoices, payments and queries rises, and the one person who did the books at the weekend cannot keep up. Invoices go out late, debtors are not chased, and management figures arrive weeks after month end. Cash tightens even though sales are healthy.
Which finance work scales with volume?
The transactional layer scales with volume: raising sales invoices, matching payments, chasing overdue accounts, entering supplier bills, preparing payment runs and reconciling the bank. These tasks follow rules and can be measured by count, turnaround and error rate, which makes them suitable for a managed team.
- Sales invoicing and statements.
- Credit control and payment chasing.
- Supplier bill entry and matching.
- Bank and card reconciliation.
- Expense processing.
What must stay under your control?
Control must stay inside the business. A named person approves payments, holds bank authority, signs off write-offs and reviews the monthly numbers. Separate the person who prepares a payment from the person who approves it. That separation of duties matters more, not less, when part of the work is outsourced.
How does chasing payments affect growth?
Chasing payments is growth finance for a small firm. Cash collected a fortnight sooner funds stock, wages and marketing without borrowing. UK law allows businesses to charge statutory interest of 8% above the Bank of England base rate on late commercial payments, but polite, consistent chasing from the day an invoice falls due is more effective.
Want a credit control routine set up and run for you? Send us your debtor days on WhatsApp.
Chat on WhatsApp →What does scaling finance this way cost?
Managed finance administration is usually priced per hour or per transaction. Indicative market ranges for managed back-office teams are £9–£18 per hour offshore and £20–£35 per hour onshore. Regulated work, such as statutory accounts and tax advice, remains with your accountant and is priced separately.
When should you build finance in-house?
Build finance in-house when the business needs daily commercial analysis, has complex stock or project accounting, or is preparing for investment or sale and wants a full-time finance director. Until then, a part-time finance lead with a managed processing team gives control without a department.
What does this look like in practice?
A pattern we see in UK firms of 10 to 30 people: invoices are raised in a batch at month end because nobody has time during the month, so customers pay a month later than they could. Moving invoicing to the day the job completes, and chasing on a fixed schedule, shortens the wait for cash without any change in sales.
Scaling finance checklist
Set these up before volume doubles.
- Invoices raised within one working day of completion.
- A written chasing schedule from the due date.
- Preparer and approver separated for all payments.
- Bank access limited to named people.
- Weekly cash position sent to the owner.
- Month end closed within ten working days.
- A data processing contract with any provider.
Next step
Tell us your monthly invoice and bill volumes, and how long month end takes. We will outline which tasks could run through a managed team and what controls to keep.
Message us on WhatsApp for a finance operations review, or book a 30-minute consultation.
Chat on WhatsApp →Sources and further reading
- Late commercial payments: charging interest and debt recovery · GOV.UK
- Contracts and liabilities between controllers and processors · Information Commissioner's Office
- Running a limited company: company and accounting records · GOV.UK
Frequently asked questions
How should a small business structure its finance function?
A small business can structure finance in three layers: transaction processing, control and advice. Processing covers invoicing, chasing and reconciliation. Control covers approvals and review by a named person inside. Advice covers tax and statutory accounts from an accountant. Only the control layer must sit in-house.
Can finance administration be outsourced safely?
Yes, with clear controls. Keep payment approval and bank authority with your own people, give the provider only the system access the task needs, separate preparation from approval, and put a data processing contract in place. Review a monthly reconciliation and a sample of transactions.
When does a small business need a finance director?
A small business needs finance director input once decisions about pricing, cash, funding and investment become frequent. That is often at 10 to 20 staff. It does not have to be full-time: many firms use a fractional finance director for a few days a month.
What is the difference between bookkeeping and finance operations?
Bookkeeping records transactions accurately in the accounts. Finance operations is wider: it includes raising invoices promptly, collecting cash, paying suppliers, reconciling accounts and producing regular management information. As a business grows, the operations side is where volume and delay build up.
Written by
Global Bridge Labs (GBL) is a UK–Sri Lanka partner for social media, websites and BPO. Everything here comes from client delivery, not theory.